Every pre-IPO opportunity arrives with a number attached. The company is valued at so many crore, the round was led by a name you recognise, the growth rate is on slide four. None of that describes the instrument you are being offered.
The capital structure does, and it is usually further back in the data room.
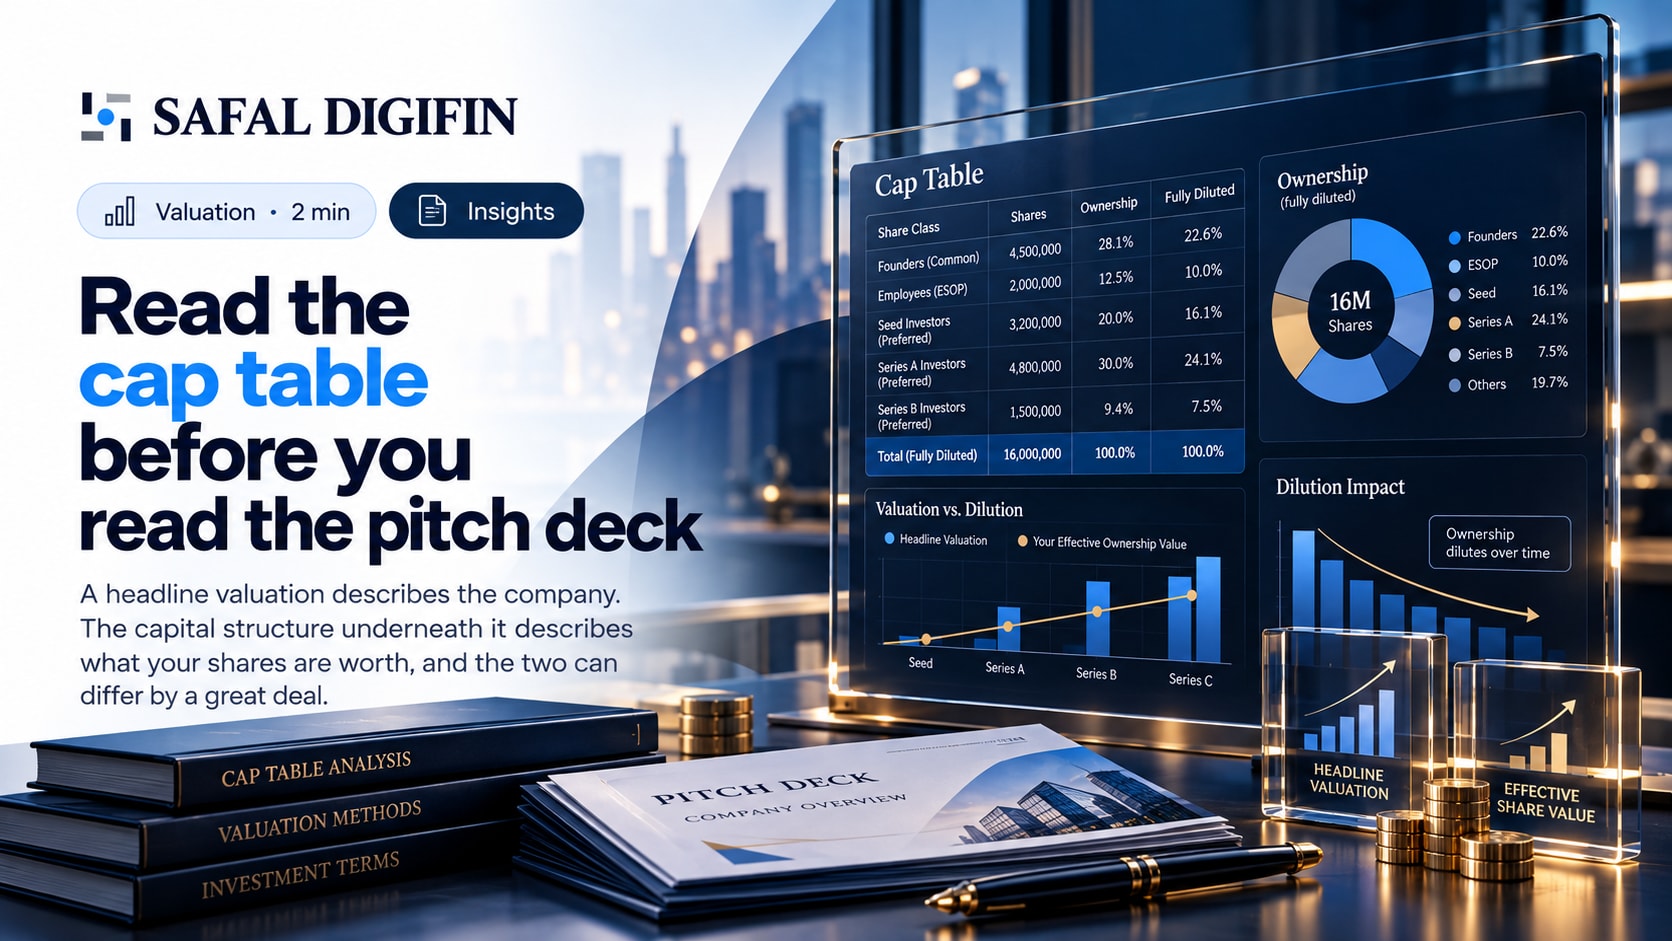
The preference stack decides who is paid first
Most private rounds are not ordinary shares. They are preference shares carrying a liquidation preference: in an exit, that investor is repaid before common shareholders receive anything. A 1x non-participating preference returns the amount invested. A participating preference returns it and then shares in what is left.
Stack several rounds of that on top of each other and the arithmetic turns unfriendly quickly. A company that exits at its last round valuation can return the full amount to preferred holders and very little to common.
The headline valuation is what the company is worth. The preference stack is who gets it. Confusing the two is the most expensive mistake in private markets.
Three things that dilute quietly
The ESOP pool. Often expanded immediately before a round and counted in the pre-money, so existing holders fund it rather than the incoming investor
Convertible notes and SAFEs. They do not appear as equity until they convert, usually at a discount, and usually at the moment the price is highest
Anti-dilution protection. A full-ratchet clause reprices an earlier round down to any lower subsequent price, and the shares to do that come from everyone else
What to ask for
A fully diluted cap table, as of today, showing every class of share, the preference terms attached to each, the unallocated ESOP pool, and every instrument that converts. Then ask for the waterfall: at a given exit value, what does each class actually receive.
If a waterfall is not available, that is itself the answer. It is a calculation the company has certainly done for itself.
The listed comparison still applies
A listed share carries no preference above it. When a private entry price is compared to a listed peer's multiple, the comparison is only fair once the preference stack is accounted for, because the two instruments are not the same thing wearing different labels.
This note is educational and describes how instruments are structured generally. It is not a comment on any specific company or transaction.
Important
This note is published for information only. It is not investment advice, an offer, or a recommendation to buy or sell any security. Investments in Alternative Investment Funds involve significant risk, including the possible loss of principal. Past performance does not guarantee future results. This communication is intended solely for sophisticated investors as defined under the SEBI (Alternative Investment Funds) Regulations, 2012. Minimum investment thresholds apply. This is not an offer or solicitation to buy or sell securities. Please read the Private Placement Memorandum carefully before investing.
Questions on this note?
Speak to the investment team